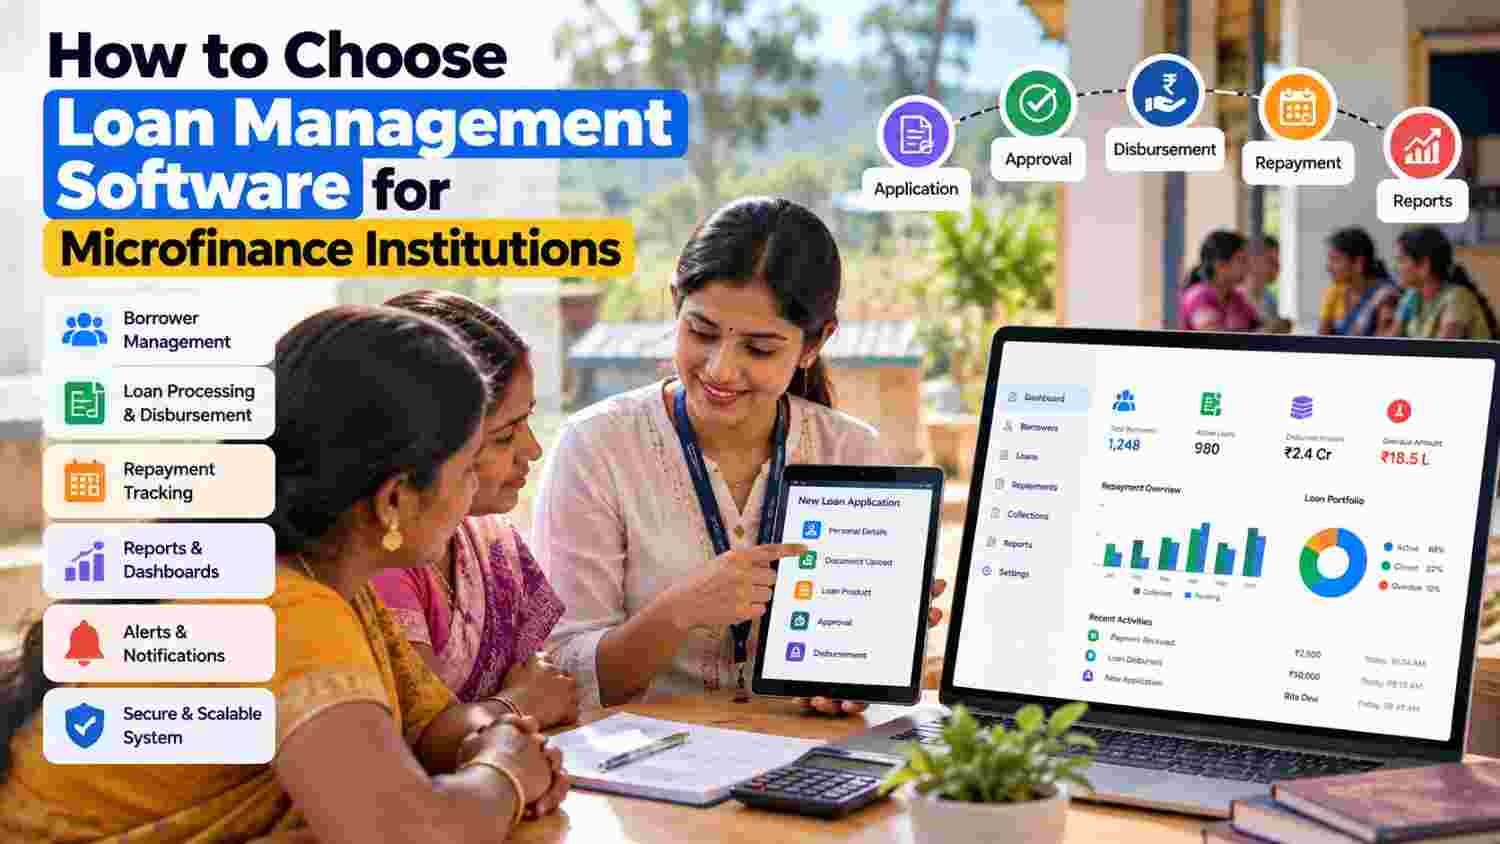
How to Choose Loan Management Software for Microfinance Institutions
- Home
- How to Choose Loan Management Software for Microfinance Institutions
Published: October 12, 2026
Last Updated: October 12, 2026
Loan Management Software for Microfinance Institutions helps lenders manage borrower records, loan applications, disbursements, repayment schedules, collections, and reports through a centralized system. The right software can reduce manual work, improve record accuracy, and help teams monitor loan accounts more efficiently.
However, every institution has different operational needs. Therefore, before selecting a platform, evaluate its loan tracking features, repayment management, field-team access, reporting, integrations, security, scalability, and support.
The best choice is not necessarily the software with the longest feature list. Instead, choose a system that supports your actual lending process and can grow with your institution.
To choose suitable loan management software, identify your institution's lending workflow first. Then assess how each platform handles borrower onboarding, loan approval, disbursement, repayment collection, reporting, data security, and integration with existing systems.
A practical selection process looks like this:
Business Requirements → Feature Evaluation → Live Demo → Integration Checks → Security Review → Cost Comparison → Final Selection
In addition, ask vendors to demonstrate your actual workflow rather than relying only on presentations or feature lists.
Choose software based on your lending workflow and borrower-management needs.
Review loan tracking, disbursement, repayment, and collection features.
Check whether field staff can access the system on their devices.
Evaluate reports, dashboards, alerts, and payment integrations.
Review user permissions, backups, security, and data ownership.
Confirm that the system can support future branches and business growth.
Compare setup, implementation, maintenance, and integration costs.
Test the software using realistic scenarios before committing.
Verify regulatory requirements with your institution's compliance team.
Do not assume that software alone guarantees regulatory compliance.
This guide is for microfinance institution (MFI) owners, directors, operations managers, branch managers, collections teams, and IT or procurement professionals comparing loan management software. Use it when replacing spreadsheets, upgrading an existing loan system, expanding branches, or evaluating vendors for individual and group lending. It is especially useful when growing borrower volumes, field collections, repayment tracking, reporting, integrations, or data-security requirements become difficult to manage manually.
Loan management software is a digital system used to manage loan accounts throughout their lifecycle, from application and approval to disbursement, repayment, and closure.
For microfinance institutions (MFIs), the system may also support borrower records, group lending, repayment schedules, field collections, payment reminders, and branch-level reporting.
For example, a field officer may record a borrower's payment while the office team checks the outstanding balance and collection report. With a properly configured system, both teams can work with consistent records instead of relying entirely on separate spreadsheets and paper files.
Nevertheless, the exact capabilities depend on the software selected and how it is configured.
Microfinance operations can involve many borrowers, recurring repayments, field staff, branches, and different loan products. As a result, managing everything manually can become difficult as the institution grows.
Common operational challenges include:
Missing or inconsistent borrower records
Errors in repayment entries
Difficulty tracking overdue accounts
Delays in preparing reports
Limited visibility into collection performance
Repeated manual data entry
Difficulty coordinating field and office teams
A centralized loan management system can help organize these activities. Moreover, it can give managers a clearer view of outstanding balances, payment status, and operational performance.
However, improvements depend on accurate data, appropriate processes, staff training, and the quality of the implementation.
The system should maintain organized borrower profiles and relevant documents.
Look for features such as:
Borrower registration
Contact and identification records
Document uploads
Group and individual borrower records
Application status tracking
Verification workflow
Additionally, check how the system handles access to sensitive borrower information. Only authorized users should be able to view or update information relevant to their responsibilities.
The software should help staff record loan applications, track approval stages, and maintain disbursement records.
Depending on your institution's process, useful capabilities may include configurable loan products, interest settings, repayment terms, approval workflows, and disbursement status.
Ask the vendor to demonstrate the complete process using a sample loan. That way, you can verify whether the system supports your existing workflow instead of assuming every advertised feature will fit your needs.
Repayment management is a core requirement for many microfinance institutions.
The software should help teams review:
Scheduled instalments
Payment due dates
Amounts received
Outstanding balances
Overdue instalments
Repayment history
Furthermore, check how the system handles partial payments, failed transactions, corrections, and reconciliation.
These scenarios matter because actual collections do not always follow the expected schedule.
Field operations can require staff to record collections, review assigned accounts, and communicate payment updates.
Depending on the operating environment, look for mobile access, collection-entry controls, location-related features, and reliable data synchronization.
If your staff work in areas with inconsistent internet connectivity, ask specifically whether offline data entry and later synchronization are supported. Do not assume that mobile-friendly software automatically works offline.
Useful reports can help managers understand both financial and operational performance.
Evaluate whether the software can generate reports covering:
Disbursements
Repayments
Outstanding balances
Overdue accounts
Branch performance
Collection activity
Staff activity
Income and expenses, where supported
Also, ask whether reports can be filtered by date, branch, loan product, or staff member.
Clear reporting makes it easier to identify discrepancies and investigate operational problems.
Reminders can help keep borrowers and staff informed about relevant events.
Depending on the platform, alerts might cover due dates, payment receipts, application status, or overdue accounts.
Before choosing a system, confirm which communication channels it supports, such as SMS or email, and whether message costs are charged separately.
Many institutions need software to work with payment services and other business systems.
Potential integrations include:
Payment gateways
UPI or other digital payment methods
Recurring-payment systems
Credit bureau services
Accounting software
Customer communication tools
However, an integration listed in a proposal should not be treated as proof that it will work with your exact setup. Ask the vendor to demonstrate the required integration, including failed transactions and reconciliation.
Microfinance systems can contain sensitive borrower and financial records. Consequently, security should be evaluated before selecting a provider.
Check whether the system offers:
Role-based access
Strong authentication
Data encryption
Activity logs
Backup and recovery procedures
Secure data exports
A documented incident-response process
Also, ask how access is removed when an employee leaves and how your institution can retrieve its data if the contract ends.
Your institution may add branches, borrowers, loan products, or new operational processes over time.
Therefore, check whether the software can support your expected growth without requiring a complete replacement.
Ask about configurable workflows, additional users, branch management, language options, and future integrations. Importantly, clarify which changes are included in the quoted price and which require additional development.
Different systems may suit different operational requirements.
This is a practical comparison, not a universal ranking. Your final choice should depend on your institution's requirements, technical resources, and operating model.
Document how applications, approvals, disbursements, repayments, and account closures currently work.
Next, identify where staff spend unnecessary time or make repeated entries. This gives you a clear set of requirements to evaluate.
Create two lists: features your institution must have and features that would be useful later.
For example, accurate repayment tracking may be essential, while an additional dashboard may be optional during the first phase.
This approach helps prevent you from paying for features that your team will not use.
Ask each shortlisted vendor to demonstrate the same workflow.
Use a sample borrower, create a loan, record a disbursement, enter a repayment, and generate a report. Then test what happens when a payment entry needs correction.
A practical demonstration is more useful than a feature list alone.
If you currently use spreadsheets or another system, find out how existing records will be transferred.
Ask about data mapping, duplicate records, incomplete fields, validation, and final reconciliation.
Before launch, confirm that balances and borrower records match the approved migration results.
Ask how user permissions, backups, audit trails, data retention, and information protection will be managed.
For Indian institutions, check the rules applicable to your legal structure and lending activities against the relevant Reserve Bank of India microfinance loan directions and subsequent updates, including the RBI's 2025 review of qualifying-asset criteria for NBFC-MFIs.
Software can support recordkeeping and operational controls, but your institution remains responsible for meeting the requirements that apply to it. Obtain advice from your compliance team rather than assuming a vendor's claims guarantee compliance.
The initial software price is only one part of the decision.
Request a written quote that separates included services from additional charges. As a result, you can compare vendors more fairly.
Before signing, clarify response times, support channels, escalation procedures, backup responsibilities, and service availability.
Also, confirm that your institution can access and export its records in a usable format. Clear ownership terms make future changes easier to manage.
Choosing only by price: A low quote may exclude migration, integrations, or ongoing support.
Trusting unverified features: Ask for a demonstration rather than relying only on sales claims.
Ignoring field conditions: Mobile access may not be enough if staff need to work with unreliable connectivity.
Overlooking data migration: Incorrect balances or borrower records can create operational problems after launch.
Assuming software guarantees compliance: Review the controls and responsibilities with your compliance team.
Skipping staff training: Even useful software can be difficult to adopt when employees do not understand the workflow.
Ignoring exit arrangements: Confirm how your data will be returned if you change providers.
Tulyarth DigiWeb's microfinance software solutions describe capabilities including loan management, borrower onboarding, repayment tracking, reporting dashboards, alerts, mobile access, and selected payment or credit bureau integrations.
Before making a decision, discuss your specific loan products, workflows, reporting needs, and required integrations with the provider. Ask for a demonstration using representative scenarios, so your team can verify suitability.
You can also learn more about Tulyarth DigiWeb before evaluating your options.
Choosing Loan Management Software for Microfinance Institutions begins with understanding how your institution manages borrowers, loan applications, disbursements, repayments, collections, and reporting.
First, document your requirements. Next, compare the essential features, test realistic workflows, assess security, confirm integrations, and calculate the full implementation and maintenance costs.
Finally, select a provider that can demonstrate how its system fits your operational needs and explain what support will be available after launch.
The right software should make everyday lending operations easier to manage while giving your team clearer records and better operational visibility.
For institutions evaluating a microfinance software solution, contact Tulyarth DigiWeb about your loan management requirements.
You may also find these articles helpful: